Coverage Built Around Your Family
Indexed Universal Life
Build cash value while protecting your family. IUL policies offer growth potential tied to market indexes with downside protection and tax advantages.
Learn More → about Indexed Universal LifeTerm Life / Mortgage Protection
Keep your family in their home even if you can't make the payments. Protect your most valuable asset with term life coverage.
Learn More → about Term Life / Mortgage ProtectionFinal Expense
Don't leave your family with the burden of funeral costs. Plan ahead with affordable final expense coverage.
Learn More → about Final ExpenseAnnuities
Build a reliable income stream for retirement. Grow your savings with guaranteed, tax-deferred options.
Learn More → about AnnuitiesIRA and 401(k) Rollovers
Consolidate old 401(k)s and IRAs into one secure account. Simplify your retirement planning today.
Learn More → about IRA and 401(k) RolloversEstate Planning
Protect your legacy and ensure your assets are distributed according to your wishes. Plan for your family's financial future beyond your lifetime.
Learn More → about Estate Planning
Indexed Universal Life
Build cash value while protecting your family. IUL policies offer growth potential tied to market indexes with downside protection and tax advantages.
How it works
An IUL is permanent life insurance with a cash value component. Part of your premium funds the death benefit; the rest goes into an account that credits interest based on the performance of a market index. When the index rises, your account is credited up to a cap. When it falls, a floor protects you — typically at zero, so a down year doesn't reduce what you've built.
What to consider
Caps limit your upside in strong years, and the policy has costs that come out of cash value. IUL rewards patience — it works best when funded consistently over a long horizon. It's a poor fit if you need maximum death benefit per dollar today; term does that better.
Who it's for
- Families who want permanent coverage rather than a policy that expires
- People who've maxed out other tax-advantaged accounts
- Anyone who wants market-linked growth without direct market risk
- Business owners planning for succession or key-person coverage
Term Life / Mortgage Protection
Keep your family in their home even if you can't make the payments. Protect your most valuable asset with term life coverage.
How it works
This is term life insurance sized to your mortgage. If you die during the term, the benefit gives your family the means to pay off the loan or keep making payments. The money goes to your beneficiary, not the lender — so they decide what to do with it.
What to consider
Coverage ends when the term does, so match the term to your remaining years. It's not a separate product category so much as term life with a specific job — if you have other needs too, one larger policy is often simpler and cheaper than several small ones.
Who it's for
- New homeowners with a large balance and years left on the loan
- Single-income households where the mortgage depends on one earner
- Families whose employer coverage wouldn't cover the house
- Anyone whose main worry is their family staying in the home
Final Expense
Don't leave your family with the burden of funeral costs. Plan ahead with affordable final expense coverage.
How it works
A small permanent life policy — usually between $5,000 and $25,000 — meant to cover funeral costs, burial or cremation, and the bills that arrive in the weeks after a death. Premiums stay level, coverage doesn't expire, and qualifying is typically much easier than for a larger policy. Many are issued with a few health questions and no exam.
What to consider
Cost per dollar of coverage is higher than a fully underwritten policy, which is the tradeoff for easier approval. Some policies have a waiting period before full benefits apply. If you're in good health and need meaningful coverage, look at term or whole life first.
Who it's for
- Older adults who no longer need income replacement
- Anyone who's been declined for larger coverage
- People who want funeral costs handled rather than left to their kids
- Families without savings set aside for end-of-life expenses
Annuities
Build a reliable income stream for retirement. Grow your savings with guaranteed, tax-deferred options.
How it works
You contribute — in a lump sum or over time — and the money grows tax-deferred. Later you convert it into income, either for a set period or for the rest of your life. That second option is what makes annuities distinctive: an income stream that doesn't stop because you lived longer than expected.
What to consider
Annuities are long-term commitments. Most carry surrender charges if you withdraw early, and terms vary widely between products. Guarantees depend on the issuing insurance company's financial strength. Read the surrender schedule before you sign anything — this is the product where the fine print matters most.
Who it's for
- People approaching retirement who want income they can count on
- Savers who've filled up their 401(k) and IRA contributions
- Anyone worried about outliving their savings
- Retirees who want a stable base underneath their other investments
IRA and 401(k) Rollovers
Consolidate old 401(k)s and IRAs into one secure account. Simplify your retirement planning today.
How it works
When you leave a job, the retirement account stays behind. A rollover moves it into an IRA or another qualified account you control. Done as a direct transfer, it isn't a taxable event — the money never passes through your hands.
What to consider
Rollovers have rules, and getting them wrong is expensive. A direct trustee-to-trustee transfer avoids withholding and the 60-day deadline that trips people up. Old employer plans sometimes have advantages worth keeping — institutional pricing, or better creditor protection in some states. Compare before you move.
Who it's for
- Anyone with retirement accounts at former employers
- People who've changed jobs several times and lost track
- Savers who want fewer statements and one clear picture
- Anyone whose old plan has limited options or high fees
Estate Planning
Protect your legacy and ensure your assets are distributed according to your wishes. Plan for your family's financial future beyond your lifetime.
How it works
Estate planning decides what happens to what you've built. Life insurance does specific jobs inside that plan: it creates liquidity so heirs aren't forced to sell property to cover taxes or debts, it equalizes inheritances when the main asset is a house or a business that can't be split, and it can fund a trust on your terms.
What to consider
This is where insurance meets law and tax, and no one profession covers all of it. We work alongside your attorney and CPA rather than in place of them. Baldwin Insurance Agency does not provide legal or tax advice.
Who it's for
- Families whose wealth is concentrated in property or a business
- Parents who want to leave children equal shares of unequal assets
- Anyone supporting a family member with long-term needs
- People who want their wishes followed without a court deciding
Carriers We Represent
Baldwin Insurance Agency is independent. We place coverage with a wide range of carriers, which means the recommendation fits your situation rather than a single company's product shelf.
- AIG/Corebridge Financial
- Aflac
- Allianz
- American Amicable/Occidental
- American Equity
- Americo
- Ameritas
- Annexus
- Assurity
- Athene
- Baltimore Life
- Citizens/CICA Life
- Clear Spring Life & Annuity
- Columbian Life Group (CFG)
- Columbus Life
- F&G Life
- Foresters Financial
- Guarantee Trust Life
- Guaranty Income Life (GILICO)
- Liberty Bankers
- Lincoln Financial
- Mutual of Omaha
- Nassau Re
- National Life Group
- North American
- Ohio State Life
- Royal Neighbors
- SILAC Insurance Company
- Sagicor
- TransAmerica
- Washington National
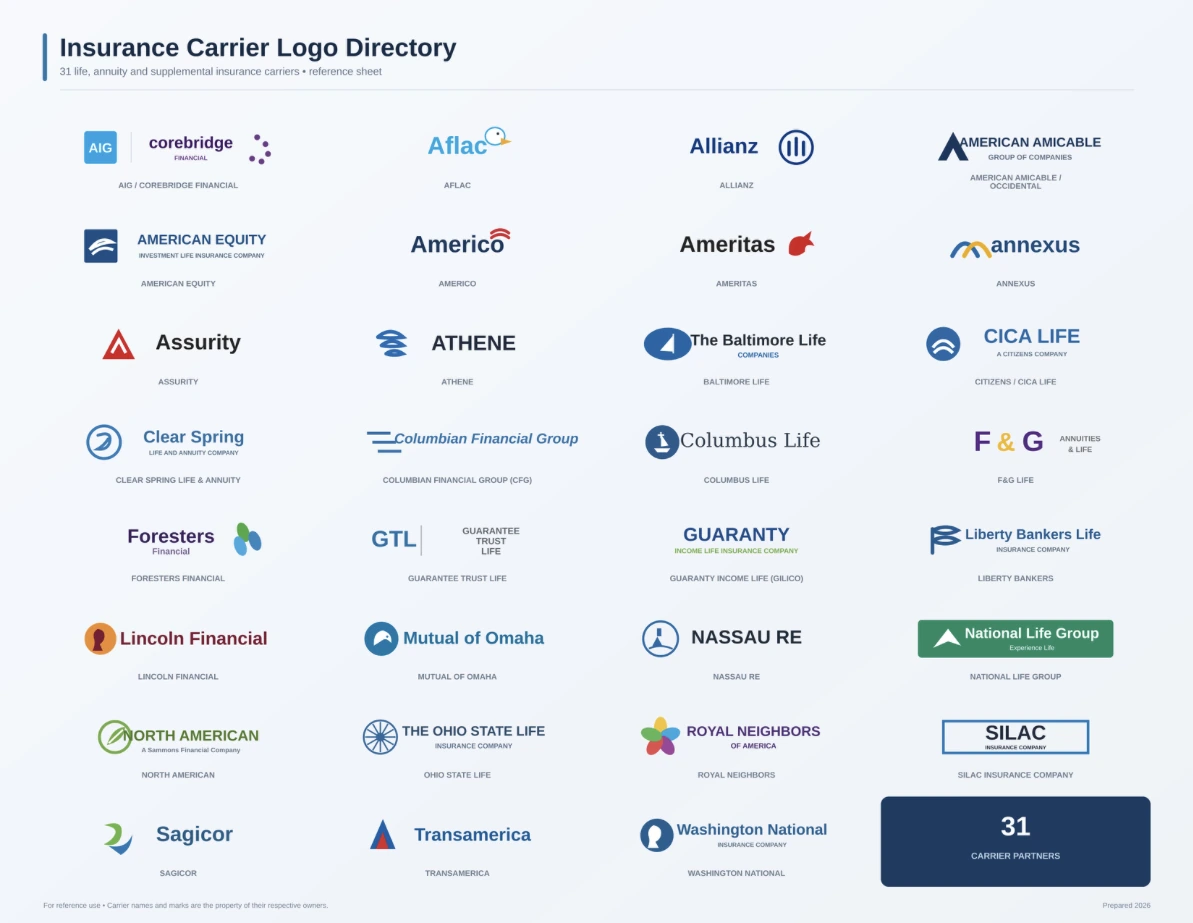
Carrier availability varies by state and by product.
Coverage options, availability, and terms vary by state and by individual circumstances. This page is general information, not a recommendation. Talk with a licensed agent about what fits your situation.